About Me

Showing posts with label JP Morgan. Show all posts

Tuesday, March 22, 2011

Entitlement Issues

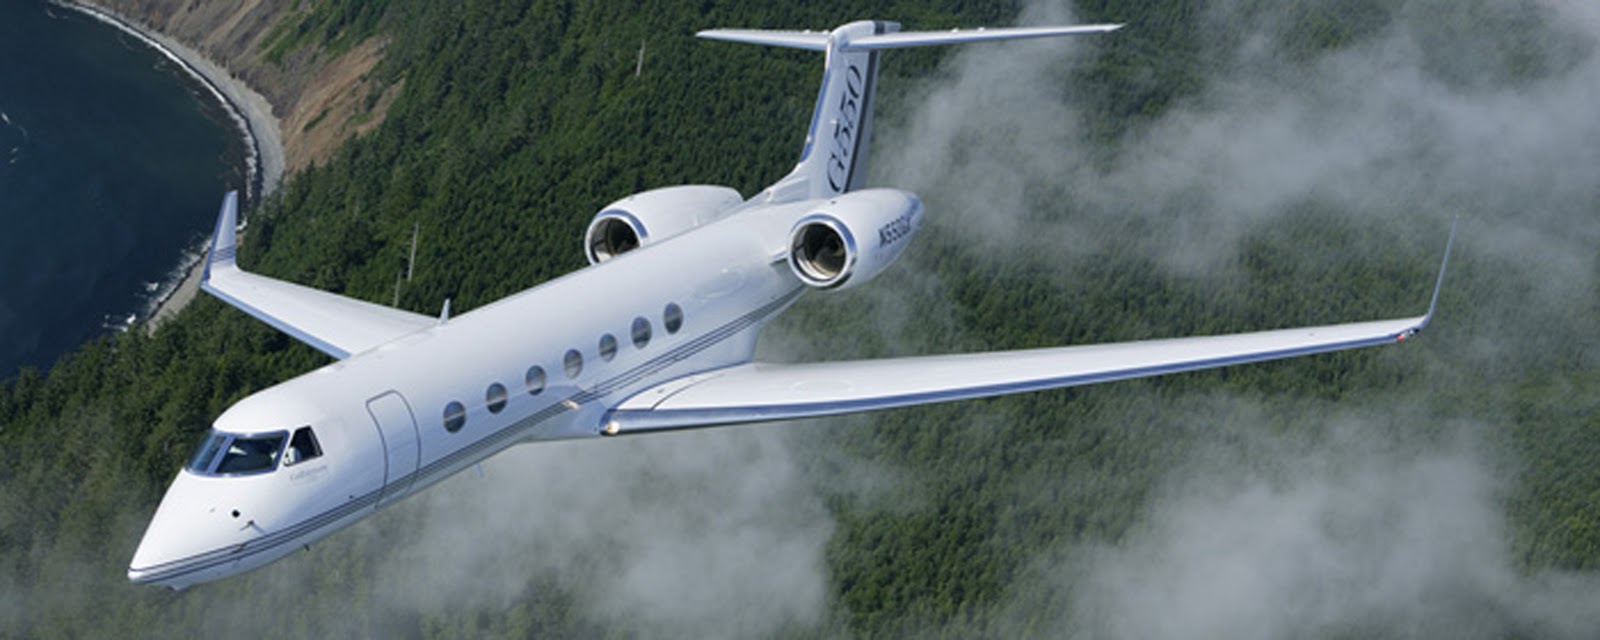
Gulfstream G550: a good place from which to suffer the slings and arrows of outrageous fortune.


People who have too much money and people who have too little share one common trait. After a time they come to believe that they deserve their fate. They settle into the trappings of their lives, and wear their circumstances like a second skin. This settling works like a self-fulfilling prophecy. The rich get richer, and the poor get poorer. What started as purely fortune, whether good or ill, becomes the natural order of things.
This all became evident to me as I struggled to make sense of my own fall from grace. I knew that the economy had collapsed, not because of any real or fundamental change in productivity or capacity or supply or demand, but because of an artificial set of circumstances precipitated largely by global financial institutions. While everyone was pointing fingers at the bursting of the real estate bubble and the huge sludge pool of underwater sub-prime mortgages, I knew that the real culprit was the enormous and mostly unregulated market in over-the-counter derivatives, speculation in which had allowed, even forced, the underwriting of the toxic mortgage paper, which in turn had fueled the real estate bubble, which in turn brought us all low when it burst.
The great irony in all this is that the investment bankers and speculators who brought us this mess escaped with our money. They fleeced us. Treasury and the Fed helped them do it. The big audit firms blessed the ubiquitous bookkeeping legerdemain. And when their overvalued and under-performing assets became problematic, we bailed them out. I've written about all this before. So have a lot of other people. If you'd like to sort all this out for yourself, I recommend the following:
  • Too Big to Fail – Andrew Ross Sorkin
  • Freefall – Joseph E. Stiglitz
  • 13 Bankers – Simon Johnson
  • The Devil's Casino – Vicky Ward
  • Griftopia – Matt Taibbi
These are by no means exhaustive, but they do, together, convey the broad sense not only of what went wrong and why, but that nothing that was broken has been fixed in any real, meaningful way. You should not read the last three without taking your blood pressure medication.
The tragedy is that, even though the contributory problems still lie festering under the surface, nobody cares anymore. The economy is recovering. The markets are orderly. We've got other problems to occupy our collective consciousness. The Middle East is in flames. Japan is radioactive. Charlie Sheen is taking us all to school in a completely different kind of China Syndrome. Who has time to worry about something that happened three years ago, even if many of us are still trying to crawl out of the smoking ruins of our former lives. It's apparently time to move on. I'm trying, but moving on is about as easy as loving my enemies or turning the other cheek.
When I first lost my job, the Lehman Brothers collapse was all over the news. The Lehman debacle was the precipitating event, the end of the beginning, the thing that galvanized the movers and shakers in government and on Wall Street to come together and save themselves from the disaster they had created. These were historic events: rewriting Fed rules to allow the lending of funds to investment banks and insurance companies, death spiral deal making facilitated by government functionaries who came from and would return to the institutions they were regulating, the sale of the TARP program (a one-page legislative mandate) to a panicky Congress by a credible Chicken Little. I was enthralled, and, being unemployed, I had plenty of time to immerse myself in the heady details.
I'd like to say that I learned, among other things, how the other half lives, but it's not the other half. It's more like the other 0.00001%. I learned how the guys in the ethereal high plains of self-entitlement live. They are not like you and me. They may have been once, but no more. They no longer carry the burden of living and working at the sufferance of others. They are the ones who do the suffering, and they do it from high-rise glass office towers, multimillion dollar Manhattan apartments, the custom appointed cabins of their Gulfstream G-550's, and palatial estates where their wives enjoy closets that are bigger than my house.
The most disconcerting thing about all of this is that it became obvious to me that these folks honestly believe that they deserve everything they have and more. They actually think they got where they are because they are smarter, more industrious, better prepared, more enlightened, and ultimately more deserving than the rest of us. They have bought in, wholesale, to their own bullshit, and they are occupied, full-time, curating their singular circumstances.
The rest of us let them do it. We've bought into their bullshit as well. We think they deserve what they've accumulated, and mostly just because they managed to do it without going to jail. So when Jamie Dimon of JP Morgan Trust says we don't need any more banking regulation, we don't think that maybe Jaime's not ready to put down the fleecing sheers just yet. Instead we think, he's smart and he's rich, he must know what he's talking about. And, when Lloyd Blankfein of Goldman Sachs says they didn't bilk their investors out of billions by selling them bundled mortgages that had been hand selected by the firm that stood to profit most if they defaulted, and that their investors were sophisticated speculators who should have been able to figure out what Goldman wasn't telling them, we don't think he's talking out of both sides of his mouth at once. This is Goldman Sachs, for crying out loud, not some fly-by-night investment chop shop like Bernie freaking Madoff.
People listen to people with money. It hardly matters what they say. This is why Donald Trump is able, with a straight face, to tell us that one of his most attractive qualities as a candidate for the Presidency is that he's rich. He apparently believes this is sufficient to convince us of his sincerity, intelligence, leadership, and good judgment in spite of the overwhelmingly contrary evidence of his hair, and the fact that he let his marital infidelity with Marla Maples in 1990 play out on prime time network TV.
If this were all there were to it, that we listen to and believe rich people because they are rich, it probably wouldn't bear remarking. The sad thing though is the other side of the coin—that we don't listen to or believe the impoverished, the more than half that is not in the 0.00001%, the half that does not suffer in executive jets or ride private helicopters to work. Us. You and me. Hell, we don't even believe each other.
I mentioned the other day that I have ascribed to myself 1/40th the relative value of Bill Gates. By this I mean that I think that my ideas, conviviality, cleverness, and good nature, are, on average, at least 1/40th as good as his. I don't think this is a vain assumption on my part. I think your ideas, etc., are probably that good as well, and I don't even know who you are.
That being the case, I also don't think it's unreasonable for me to demand from the nebulous creative energy of the limitless universe, the deliberately secularized power behind the so-called law of attraction, that I should receive something akin to 1/40th of Bill Gates' net worth—specifically $749,000,000. If I had $749,000,000 people might actually begin to listen to me. Some of them might even read my frigging book. 


Wednesday, August 18, 2010

Day 304 – Punters and Touts

Shame on us if we don’t stop the banks from continuing to fleece the country. They will be happy to blame someone else for the problems they created. In fact they’ve already done it. Do Bank of America or Citibank or JP Morgan or Goldman Sachs take any responsibility for the financial crisis? Do they think the Great Recession has anything to do with predatory lending policies and profiteering on unregulated derivatives, or do they want to lay it all at the feet of people who defaulted on their mortgages? 
There is no way that the threat of foreclosures on subprime loans brought the global financial system to its knees. The math doesn’t work. If all the subprime loans that are going to go bad went bad on the same day, the carnage still wouldn’t add up to what we got. What we got was a ridiculous multiple of the actual problem. And the reason we got a ridiculous multiple is the extent to which the banks leveraged their own folly.
Of this amount there was still some residual value in the underlying residential real estate. Average home prices had declined about 20% by that time. If you consider that the homes with delinquent mortgages were probably in worse shape than the average home, the value lost might have been as much as 40%. So the actual losses on mortgages in default in August of 2008 was something like $400 billion. How did this amount devastate the nation’s economy and send our largest banks into a tailspin?
The answer is twofold—leverage and speculation. The five major investment banks (Bear Stearns, Merrill Lynch, Morgan Stanley, JP Morgan, Lehman Bros. and Goldman Sachs) were leveraged between 25- and 32-to-one at the end of 2007. That means for every dollar of assets they had $32 dollars of debt. They were at the limit of their capital requirements, so their leverage played heavily in determining their soundness. Because of the leverage, if a bank had a million dollars of losses in their loan portfolio and took the loss—that is marked their portfolio down to its realizable value—it would have to come up with $25 to $32 million of additional capital. As you can imagine, this is a pretty scary place to be. This is why no one wanted to write their assets down. This is why they invented accounting chicanery and subterfuge to get the bad assets off their books at full value. At this point, not that I would suggest this is what happened, even fraud would have seemed a better alternative to telling the truth. The consequences certainly would have been less onerous—a few hundred million in fines and sanctions against losing the company entirely.
Speculation just made the problem worse. While there were $10 trillion in outstanding U.S. residential mortgages in 2008, there were $47 trillion in nominal value of credit default swaps circulating in the largely unregulated over-the-counter derivatives market. No one really knew how much was outstanding because the market was unregulated. The market was unregulated because Alan Greenspan, Bob Rubin, and Larry Summers decided to keep it unregulated back in the late 90s. Not only that...they saw to it that Brooksley Born, then head of the Commodities Futures Trading Commission, was silenced for daring to suggest that an unregulated market this size might turn out to be a problem.
Today Greenspan at least admits that this was a mistake. Rubin has denied any complicity in the decisions, and in a Herculean revision of history akin to cleaning out the Aegean stables, now claims that he always thought regulation of the derivatives market was a good idea.
Credit default swaps are like insurance contracts put into place to cover the losses should some mortgages stop performing. The derivatives protect the income stream of the investment in the mortgage. If the homeowner defaults, the derivative pays off. The investor, the organization in this case that bought a package of securitized mortgages, is whole. This is the ostensible purpose of CDS, but if this were their real application why in the world would we need $47 trillion of swap contracts to protect us from $400 billion in losses? That is 117.5 times more protection than was needed.
The speculative part of the problem comes in because, in the world of derivative contracts, you don’t have to own a mortgage to insure against mortgages defaulting. These things are traded in banks and brokerage houses, but they would be more at home in betting parlors. They are not investments. They are wagers.
Derivatives are gambling in its purest form. They are perfectly analogous to a pari-mutuel ticket on a horse race. When you bet on a horse race, you do not have a stake in the horse. You have no interest or participation at all in the horse racing industry. Your only interest is in the outcome of the races on which you have bought tickets. Derivatives are the same. You are betting on the outcome of an event. You don’t have to have a stake in the event other than your contract. You don’t care about the owner of the mortgage, or its originator, or the homeowner, or the value of the mortgaged property. You only care if the mortgage stays good or goes bad. One way you win. One way you lose. Whatever else happens is not your concern.
You can buy a contract on anything. This is what our august financial institutions were doing—gambling on outcomes in which they had no stake other than the outcome. Because the market was unregulated and thus hidden from scrutiny, no one had any idea how deeply the problem ran. The banks were betting against their bets against their bets against their bets that mortgages wouldn’t go bad.
Of course the problem was that If a bunch of mortgages went bad, the companies that sold the derivative contracts were going to have to pay off three and four times...or 10...or 117. No one was prepared to do that. No one could. There wasn’t enough real value in the system to allow that to happen. The whole thing was an enormous house of cards that spun off hundreds of millions of dollars of profits over a decade or so, but which was so fragile that it would all come tumbling down in the balmiest zephyr of ill wind. That’s why now we taxpayers are going to have to pay off the losses three times over before we’re out of the woods.
This is crazy. This kind of stuff is no longer about saving the financial system or shoring up the markets against unforeseen volatility. This is about a handful of guys that we trusted because they were supposed to be the smartest guys in the room betraying that trust and using their smarts, their cultural advantages, and their connections, to systematically strip us of the wealth many of us actually worked for…and they’re still at it.
The banks are still lobbying for less regulation, still trying to keep unfettered access to derivative plays, still anxious to package and sell collateralized debt obligations, and still especially vested in remaining too-big-to-fail because that takes all the risk out of the game for them. Staying too-big-to-fail insures that they will be bailed out by the taxpayers whenever their risk models fail. They reap huge profits on inordinate risk, and we back their play. Who wouldn’t want a piece of that action?

Monday, August 9, 2010

Day 276 – Hood Ornaments

Lehman earnings before the collapse. Takes brass balls to make a hood ornament like this.
          There is nothing like a history of success as a basis upon which to build further success. By the same token, relying solely on past success to provide a clear path into a prosperous future is folly itself. Nothing persuades us quite so well as success that our instincts and abilities are sound, and nothing else is so quick to pull the rug out from under our feet.
          I have said repeatedly here that success is largely a matter of luck. There is no doubt that we can do things to capitalize on luck when it presents itself, but if luck does not present itself there is very little we can do to overcome the adversity that swallows our hopes in its absence. You can be ready for good fortune, but you cannot make it. You can even mitigate bad fortune, but you cannot unmake it.
          Still, we look to past success as an indicator of the probability of future success. We do this as investors. We do this as employers. We do this as humans. We are naturally drawn to what worked before. We are drawn to it, foremost I think, because it is familiar. We know that conditions change, and that, because of the mercurial nature of circumstances, the familiar may not serve us so well in unfamiliar territory. Yet the familiar attracts us because we do not have to think about it so much. This is a danger, but a natural inclination. We want to take the path of least resistance.
Successful executives, being for the most part human, are not much different from the rest of us in this regard. They just have a better recorded history of past successes on which to rely. This history may give them an occasional pass when they err, but it will not make them any more likely to perform up to their reputation when circumstances change. When their bubble bursts they will act and protest in the same ways and with the same results as the fools and charlatans in my past like Henry and Ivan. We have only to look at the events surrounding the collapse of our financial system to see that this is true.
          Dick Fuld, head of the ill fated Lehman Brothers, spent his time before the fall trying to get everyone to believe that Lehman’s problems had to do with irresponsible and predatory short sellers trying to profit off of lies and innuendo. He didn’t do anything to shore up Lehman’s cancerous balance sheet. He couldn’t. He’d been resting on his laurels until it was too late.
Lehman’s earnings were illusory. They were window dressing. They were like the hood ornament on a fancy car with bad valves and clogged injectors. They didn’t mean anything, and they didn’t have any substance. Still, Fuld kept touting earnings as if that should be enough to get the wolves off his back. The wolves did not desist. The scavengers among them were busy shorting his stock. The alpha dogs were demanding more and more collateral. Lehman was getting squeezed in the middle, and all the public hand wringing was just making it worse.
          The reason the wolves did not desist is that the wolves were mostly in the same boat as Fuld. They were all, and indeed they all remain almost two years later, deeply leveraged on overstated assets. An accurate valuation of their worth, individually and collectively, was problematic at best, impossible at worst. Certainly no one wanted to do it. A collective valuation that even approached accuracy would collapse the system. Everyone knew this...the bankers, the auditors, the regulators, Treasury. They just neglected to tell the rest of us. To forestall the collapse, Treasury and the Fed kept proposing ever more ridiculous mergers and absorptions to hide the mess. The NY Fed under Tim Geithner was determined to offload Lehman before it sank. Everyone Geithner approached, and indeed everyone who approached Lehman, wanted the same kind of sweetheart deal that JP Morgan got to absorb Morgan Stanley. Everyone wanted a dirt cheap price and a guarantee from the US taxpayers that they wouldn’t have to swallow any losses. All the potential buyers had enough losses of their own to worry about without buying billions more in a government sponsored fire sale.
          Eventually Lehman was hung out to dry. Treasury wouldn’t back anybody’s play. People are still arguing today about why this happened. Treasury was happy to sweeten the Morgan Stanley deal, and happy to bail everyone else out after the Lehman collapse. Why let Lehman go down the sewer?
I think it was to send a message to the rest of us, especially Congress, just how high the stakes were. In the ugly aftermath of a Lehman collapse no one was likely to question Treasury and the Fed colluding to prop up their buds and compadres at Morgan, Goldman and the rest. Certainly Paulson at Treasury used the prospect of financial chaos to shove TARP down everyone’s throat with little oversight and no accountability. There was even enough residual fear going into the first six months of the new Obama administration to have them looking like Republicans when it came to their treatment of the banks and markets. Of course when you think about it Democrats and Republicans alike use the same currency to get themselves elected.
          What we’re left with today is the same financial system that cleaned us all out two years ago, the same broken down heap with a spectacularly buffed and polished hood ornament. Admire it all you want, but don’t expect it to get you very far down the road.

Friday, July 16, 2010

Day 255 – The Ant and the Grasshopper

            I always liked the Aesop fable about the grasshopper and the ant. The ant spends the summer storing up grain and supplies for the coming winter while the grasshopper sings and plays the fiddle and, in some tellings, ridicules the ant for wasting the idyllic days with industry. When winter comes the ant is warm and well provisioned while the grasshopper is cold and hungry. When the grasshopper comes knocking on the ant’s door for a handout, he is in turn roundly castigated by the ant for wasting the plenteous days of summer with idle pursuits when he should have been working to store up provisions.
The grasshopper is turned away to die in the ancient versions of this story, and invited in to sing and dance in exchange for the ant’s largesse in some more modern iterations. I like the versions where the ant shares his bounty better than the ones where the grasshopper dies. This may be because I am now forced by circumstances to consider that I have in fact become one of life’s grasshoppers.
          There are more modern versions still—sarcastic ones but apocryphal nonetheless—where government intervenes on the grasshopper’s behalf, condemns the ant for greed and acquisitiveness, confiscates the ant’s wealth, and redistributes it to the grasshopper. The left-leaning sensibilities of our modern world, the re-spinners of this yarn would have us believe, have turned Aesop’s wisdom upside down.
          I am not a communist, not a socialist, not a Marxist. I do not believe in the forced redistribution of wealth. I do not think it is a good idea to strip the risk-takers and innovative thinkers of the comforts they have managed to accumulate for themselves by industry and perseverance and to give it to a bunch of lay-abouts in the interest of social fairness. I think doing this is an excellent way to guarantee the end of progress and the diminution of wealth and quality of life for society as a whole.
          I am still, however, as I have already pointed out several times, a vengeful bastard. So if you are talking about stripping the executive helicopter from Joe Gregory (Lehman Bros.) or the $6,000 suits from Jamie Dimon (JP Morgan) or the Manhattan apartment from Lloyd Blankfein (Goldman Sachs) or the multimillion dollar bonus from any one of several thousand bank executives and traders who profited hugely from the financial troubles that are still troubling the rest of us, and giving that stuff to me, then I say go for it. It’s only fair. After all, these scalawags precipitated a forced redistribution of wealth in the name of unabashed capitalism, and they remain, not just unrepentant, but proud of their accomplishments.
          These yahoos, just like the muddling managers I used to work for, have broken the system that sustains them, and now, while the victims of their shameful duplicities, frauds, and ignorance languish in unemployment, despair and powerlessness, they are engaged in self-congratulatory celebrations of their return to profitability. They made the hard choices, they say, they took their lumps such as they were, and emerged stronger than ever from the wreckage they caused. Who in their right mind does not believe that these lugubrious flim-flammers should be rounded up and horse whipped?
          Ah, but I digress—easy when you are a grasshopper, and even easier when you consider that, in the current circumstances, the ants have not fared very well either. In fact the ants may have suffered worse than us grasshoppers. They certainly had more to lose at the outset.
Sometimes, when I think of what might have been, I am glad that I didn’t give up the life I had at the time in order to make a better one in the future. Sure, I worked hard for what I got, but I didn’t give up as much life balance as I could have in order to accumulate stores for my future. And what I did get I mostly spent when I got it—better in retrospect than denying myself for a future that was going to be stolen from me in any event. How pissed would I be then? Pissed enough perhaps to have joined the Tea Party so I could go to rallies with crackpots and stare at Sarah Palin’s bosom.
As a grasshopper I depend on the ants. Their surplus is my birthright. Not all of it mind you, just the amount they are willing to give up for my fiddling and dancing. This is not without precedent. There are others who add no value to our economy, but still manage to fare very well on stipends for their entertainment value. Tom Cruise comes to mind, Brad and Angelina, virtually all the various Real Housewives (very few of whom it turns out really are), Paris Hilton, Perez Hilton, the Kardashians, everyone from Twilight.
These are just the most egregious examples I can think of. Arranged into categories, professional athletes, entertainers, artists and writers, celebrities of every stripe are useless in terms of their ability to add to the collective wealth of society. These people are all paid from the stores of the real producers among us, and many of them are paid very well indeed. They are paid so well that a lot of actual productive workers aspire to be just like them.
Now there is a world turned upside down, although it may be as much due to the attendant fame and sex appeal as to the pay scale. Who would not rather be tricked out in the resplendent colors of the grasshopper above than the drab monochromatic uniform of the fire ant I wrote about some days ago? On the other hand, if one were going to try to relieve Jamie Dimon of one of his resplendent suits, who would not rather have the formidable resources of the fire ant at his disposal? The fire ant’s arsenal though is the exclusive preserve of power mongers and rebels. In the world where I live, the world where fables are mostly just entertainment, the ants would mostly rather be grasshoppers.